Credit opens the zip and finds six title numbers, a rent roll and one company number that does not own any of them. The covering email says the book sits in “the SPV”. The Companies House overview shows a different company as proprietor on three titles and a dissolved sister vehicle still named in the draft charge schedule. The portfolio finance file does not die on LTV. It stalls on who actually borrows and who can grant the charges.
StatusKWO prices short unregulated commercial facilities for professional property investors, developers and corporate borrowers. Consumer owner-occupier credit sits outside that perimeter. Published terms currently show a monthly rate from 1.25%, an entry fee of 2%, an exit fee of 1.5%, LTV up to 85%, loans from £10,000 to £10,000,000+ and terms up to 16 months. Those are schedule figures. They are not a promise that every multi-company stack prices at the floor.
The company search that stalls a portfolio DIP
A multi-title bridge is underwritten as a security stack, not as a colourful spreadsheet of addresses. Who owns each title. Which company will be the borrower. Which companies will grant first legal charges. Which directors will guarantee. If those four answers disagree, the decision in principle comes back as questions.
Our rent roll pack covers income evidence. The general packaging guide covers a single-file first email. This page is narrower. It is the Companies House and SPV evidence that should sit in the first zip when more than one company or more than one charged title is in play.
Start with one page. Borrower company name and number. Registered office. Directors. Guarantors. Each charged title with its registered proprietor. Gross and net loan. Term. Use of funds. Named exit. Then attach the company papers before the floor plans. Credit can read a floor plan later. They cannot invent a company number from a broker nickname.
A portfolio bridging enquiry that mixes personal names, old trading styles and two live SPVs without a structure sketch wastes a day. Draw the stack. Parent. Borrowing SPV. Charging SPVs. Dormant shells that still hold a title. Leave nothing for the underwriter to reverse-engineer from five PDFs named “scan final v3”.
Public data helps. It does not replace the pack. Credit will still open Find and update company information and the Companies House register search guidance. They want your pack to match what the register already shows. Mismatch is delay.
What belongs in the first SPV zip
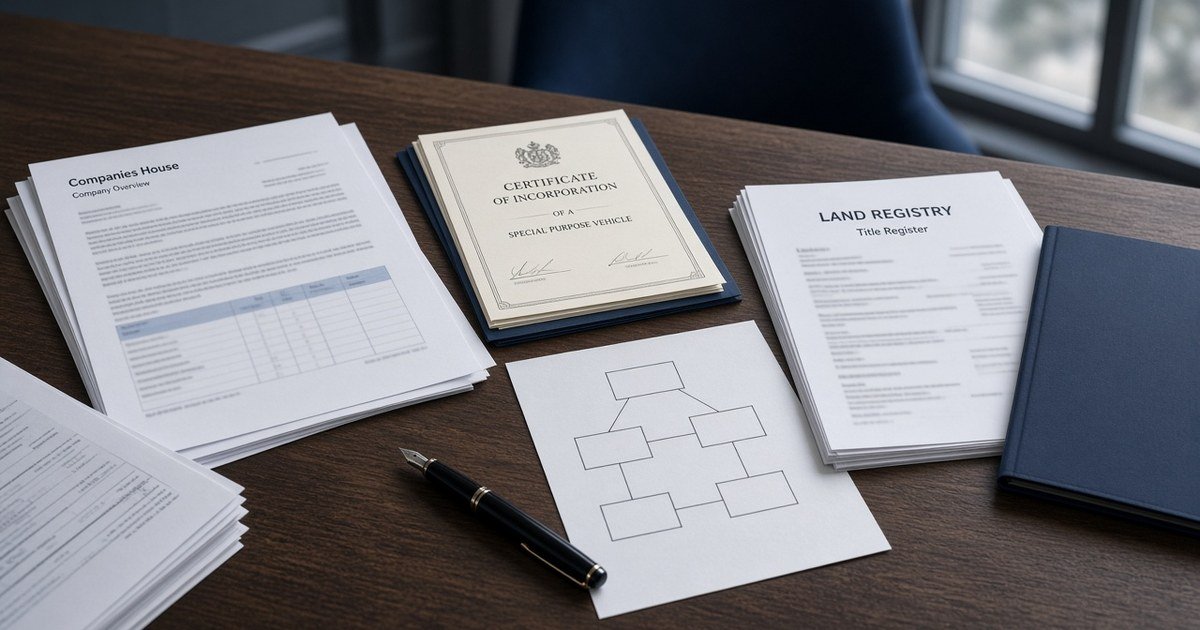
Send the certificate of incorporation for every company that borrows or grants security. Current articles of association. Full list of directors and shareholders. Confirmation statement or recent statement of capital if the share position has moved. Registered office that matches the facility paperwork. A dormant company that still owns a title still needs those papers. Silence is not comfort.
Identity for every director and every named guarantor belongs in the same zip. Clear passport or photocard licence. Proof of address dated inside three months. HMRC’s public baseline on customer due diligence under the Money Laundering Regulations still asks for name, photograph on an official document, residential address and date of birth. It also requires beneficial owners where a company sits in the structure. Cropped selfies and expired cards come back.
Source of funds sits next to identity. Deposit money, refinance proceeds, director loans and sale receipts need a trail. A round-sum credit with no origin note is not a trail. If cash came from a prior sale, attach the completion statement. If it came from a director, attach the loan account or board minute and the director’s own statements. Overseas funds add time. Say so on page one.
Board minutes or written resolutions that authorise the borrowing and the charges save a solicitor chase later. Name the facility size, the charged titles and the people authorised to sign. A generic “directors may borrow” minute from three years ago is weak when the structure has changed.
If the borrower is a new SPV formed for the purchase, say when it was incorporated and where the share capital cash came from. A company incorporated last Tuesday with no bank statements yet is not impossible on an unregulated commercial bridge. It is slower. Credit needs the subscription trail and the directors’ own source of funds.
Adverse history on a company or a director is not an automatic decline on specialist commercial bridging. Unexplained dissolved companies, CCJs and unpaid charges will be asked about. Put a short written explanation in the first pack. Waiting until day four wastes a week.
PSC register and beneficial ownership that credit must match
Persons with significant control are not a footnote. GOV.UK’s PSC guidance is blunt. A company must identify who owns or controls it and tell Companies House. The register cannot sit blank. Nature of control bands for shares and voting rights matter. Over 25% up to 50%. More than 50% and less than 75%. Seventy-five percent or more.
Credit matches the PSC register to the people who will sign guarantees and to the people who control the exit. A PSC who is not in the guarantor list raises a question. A guarantor who does not appear as a PSC raises a different one. Both are answerable. Neither should arrive as a surprise after the DIP.
Relevant legal entities sitting as PSCs need the same honesty. If a holding company owns the borrowing SPV, send the holding company’s filings too. Credit will not stop at the first company number. They follow control until a natural person appears, or until a clear RLE story is on the page.
Update lag is common. PSC changes should reach Companies House within 14 days of confirmation under the public rules. If your pack shows a share transfer that the public register has not caught yet, attach the stock transfer, the updated register of members and the filing that is on its way. Do not hope credit never checks.
A PSC statement that says there is no registrable person needs an explanation in the covering note. Thin capitalisation and nominee arrangements attract questions on source of funds and control. Answer them early.
Existing charges MR01 history and priority questions
Open the charges tab before you promise a clean first charge. Companies House records mortgages and charges created by the company. GOV.UK’s guidance on registering a charge for a limited company explains why timing matters. Particulars are normally filed on form MR01. Late filing can need a court order. An unregistered charge can be worthless against a liquidator or administrator.
List every live charge on every charging company. Approximate balances. Chargee names. Whether the charge is fixed, floating or both. Whether it bites the titles you want to offer. A floating charge over “all property” still matters even when you think the asset is free. Put the redemption statement ask in the pack if a prior lender must be repaid on completion.
Land Registry title registers must agree with the Companies House story. Proprietor name. Title number. Existing registered charges. A company that appears as proprietor on the title but not as a party in your draft security schedule is a drafting error waiting to happen. A second charge or a cross-charge over supporting assets is a different file from a clean first-charge stack. Say which.
Satisfaction filings matter too. An old charge that still shows as outstanding on Companies House will delay solicitors even if the debt was repaid. Attach the DS1 or the MR04 filing if you have it. If the prior lender is slow, say that on page one and name who is chasing.
Priority deeds and intercreditor arrangements belong in the first pack when more than one lender will sit on the same company or the same title. Credit will not invent ranking from a cheerful covering email.
Share charges debentures and multi-company stacks
Property charges alone do not always finish the security story on an SPV. Many specialist facilities also take a share charge over the shares in the borrowing company. That stops a quiet sale of the SPV behind the lender’s back. Blank stock transfer forms and share certificates usually travel with that document. Name the shareholders who will grant it in the first enquiry.
A debenture or all-asset charge may sit beside the property charges on a trading or development SPV. Our older debenture overview covers the instrument family. For a let residential book the property charges and any share charge often do the heavy lifting. Say what you expect. Do not leave the security package as “whatever you usually take”.
Multi-company stacks need a simple sketch. Which company borrows. Which companies grant property charges. Which companies only collect rent. Which companies are empty shells that still hold a historic title. If rent is collected in one vehicle and title sits in another, credit needs both. Mixing them without a cross-charge note creates false comfort.
Group guarantees are common on unregulated commercial portfolio bridges. Name the guarantor companies and the natural persons. Identity for those individuals belongs with the company papers. A late request for a spouse guarantee after heads of terms is how goodwill disappears.
If one title will stay outside the charge and only support income, say so. Income without security is a different risk. The rent roll still matters. It does not replace a charge over the asset.
Auction lots bought into a fresh SPV still need the company pack on day one. The 28-day clock on auction finance does not pause while someone incorporates the vehicle after the hammer. Bring the company number to the legal pack review.
How the SPV pack meets title rent and exit evidence
Company papers do not replace title. They sit beside it. Official copies of the register and title plan for every charged asset belong in the same submission. Leasehold stock needs remaining term, ground rent, consent-to-charge wording and landlord details. A short lease that a term lender will not refinance is an exit problem. It is not trivia.
Rent evidence still decides coverage on a let book. Use the rent roll checklist. Contracted rent. Bank credits. Deposit protection. Licence status on HMO or selective licensing stock. See the HMO licensing pack when shared houses sit in the charge. A perfect Companies House filing with a fantasy rent total still fails.
LTV stays on the lender’s valuation of the charged titles. Income supports the hold case and the refinance story. It does not replace value. StatusKWO’s published maximum LTV is 85%. Many live multi-title files sit below that once lease term, works and exit quality are in the number. State gross and net advances. Retained interest and fees change what clears on day one. Published entry is 2% and exit is 1.5%. A coverage test that only clears interest on the net figure can fail once retained interest sits in the gross.
Exit evidence must name the same borrowers and the same security the bridge will create. A term-lender AIP addressed to a different SPV is decoration. Refinancing a buy-to-let portfolio with a bridging loan still needs a rent roll and a company stack the term desk will accept. Sale-led exits need marketing evidence and a realistic clock. Soft buyer demand does not kill every sale file. It kills files that assume last year’s asking price and a four-week exchange.
Development holdovers need honesty about product fit. A light refurbishment can sit on a short bridge. A heavier build programme may belong on development finance with staged drawdowns. Do not force a full build into a 16-month portfolio bridge without a costed works schedule and a drawdown story.
Brokers who submit through the broker route should keep one naming convention across every PDF. Company number in the filename. Title number in the filename. Version dates. Credit spends less time hunting and more time pricing.
Common pack errors on multi-SPV files
Wrong proprietor on the charge schedule. Title in company A. Facility and draft charge in company B. Fix it before valuation, not after.
PSC register that still shows the previous shareholder after a recent transfer. Attach the live register of members and the pending filing.
Dissolved or struck-off company still named as a charging party. Revive it properly or move the title first. Do not hope the solicitor invents a fix on completion day.
Existing floating charge ignored because “it is only a bank overdraft”. Check the instrument. Many bite all property.
Share charge promised verbally but shareholders not identified. Name them. Send certificates. Send ID.
Rent collected into a personal account while titles sit in SPVs. Explain the flow and tidy it. Credit will ask how a term lender will underwrite that book later.
Overseas directors with no UK address proof and no early warning in the covering email. Flag the KYC path on page one.
Mixing bridging and development drawdown language in one enquiry without saying which product you want. Pick a desk.
What to send before you ask for a DIP
One-page deal summary with company numbers and title numbers. Structure sketch for every company in the stack. Certificates of incorporation and articles. Director and shareholder lists. PSC position that matches Companies House or explains the lag. Identity and proof of address for directors and guarantors. Source of funds trail. Live charge list with balances. Land Registry official copies. Rent roll and tenancy evidence where the book is let. Named exit with matching borrower names. Board authority to borrow and charge.
That pack is how a multi-title portfolio bridge gets priced without a week of chasing. Incomplete packs come back as question lists. Question lists are slower than twenty minutes spent labelling the companies correctly.
If the file is ready, start with a decision in principle or speak to the desk through the broker channel. Bring the Companies House story in the first zip. Credit will open the public register anyway. Make sure your pack already matches it.
Frequently asked questions
Do I need a separate SPV for every title on a portfolio bridge?
No. Many books sit in one company. Some sit across several. Credit cares that the borrower, the charging parties and the registered proprietors match. A single SPV with clean title and a tidy rent roll is often simpler. Multi-company stacks work when the sketch and the filings are clear.
Will StatusKWO lend to a brand new SPV?
Sometimes. Unregulated commercial bridging can fund a purchase into a newly incorporated vehicle when identity, source of funds and security are clean. Expect more questions on subscription money and director history. Bring those answers in the first pack.
Is a Companies House screenshot enough?
No. Screenshots help. Credit still wants certificates, articles, PSC detail, charge lists and identity documents in a working zip. Public data confirms your pack. It does not replace it.
Do you always take a share charge on an SPV portfolio bridge?
Often on SPV borrowers, yes, because it protects against a quiet change of ownership. The exact security package depends on the file. Property charges remain the core. Share charges and any debenture sit beside them when the structure needs it. Ask early rather than assuming.
What if the PSC register is out of date after a recent share transfer?
Say so on page one. Attach the stock transfer, the updated register of members and proof that the Companies House update is filed or in hand. Do not leave credit to discover the mismatch on a public search.