The valuation cleared. The title is clean. Completion is booked for Friday. Then credit opens the deposit schedule and finds a £180,000 credit with no payer name, no sale reference and no director loan minute. The bridging loan does not die on LTV. It stalls on money nobody can explain.
StatusKWO prices short commercial facilities for professional investors, developers and corporate borrowers. Owner-occupier main-home files sit outside that set. The published schedule currently shows a monthly rate from 1.25%, an entry fee of 2%, an exit fee of 1.5%, LTV up to 85%, loans from £10,000 to £10,000,000+ and terms up to 16 months. Those figures sit on the product sheet. They are not a waiver of the Money Laundering Regulations trail that sits behind every deposit, equity injection and cash completion.
The round-sum deposit that stalls completion
A tidy decision in principle is not a funded completion. Credit still has to see where the borrower’s own money came from before solicitors can draw.
Our general bridging pack note covers identity, companies and a one-paragraph SOF ask. Yesterday’s SPV and Companies House pack covers the entity. The page you are reading is narrower. It is the source-of-funds zip a specialist desk wants before it clears deposit money, retained interest cash or a cash top-up on completion.
Start the enquiry with one page. Address and title number. Gross and net loan. Term. Use of funds. Named exit. Borrower and guarantor names. Then list every pot of cash the borrower is putting in. Deposit. Works reserve. SDLT. Legal costs. Auction deposit already paid. Write the amount, the account it sits in and the origin claim in one line each. Credit can read a brochure in five minutes. They cannot invent a trail from a covering email that says “funds from savings”.
HMRC’s public guide on responsibilities under the Money Laundering Regulations is blunt. When a business relationship starts, you need the purpose of the relationship and where funds will come from. That is not consumer mortgage theatre for this desk. It is why a round-sum inward payment with no origin note comes back as a question list rather than a funds release.
Source of funds versus source of wealth on a bridging file
Brokers mix the two labels. Credit does not.
Source of funds is the money for this deal. The deposit. The equity injection. The cash that clears SDLT and fees. HMRC’s source of funds and source of wealth manual says the question goes past which account the money left. It is how and from where the client got that money for this transaction. A UK bank account alone is not enough.
Source of wealth is the wider story. How the director built the balance sheet that makes a six-figure deposit plausible. Sale of another asset. Trading profits. Inheritance. Long employment savings. Credit asks for wealth papers when the deposit is large against known income, when the structure is complex, when a politically exposed person sits in the file, or when enhanced checks already apply. Do not wait for the solicitor to raise it on day four.
Put both labels on the one-pager if both are in play. “Deposit £120,000 from sale of 14 Acacia Road, completion 12 Aug 2026” is source of funds. “Director built equity through three BTL disposals 2022 to 2025” is source of wealth. One sentence for each beats a vague “high net worth individual” line that forces a chase.
Identity still sits beside the trail. Passport or photocard licence. Proof of address. For an SPV, the company and PSC papers from the Companies House pack. SOF does not replace KYC. It sits on top of it.
Bank statements that prove possession not origin
Three months of statements are the usual ask. They prove the money is in an account the borrower controls. They do not, on their own, prove how it got there.
Credit reads the credits first. Salary. Rental receipts. Sale proceeds. Director loan. Gift. Transfer from another own account. Then the large unexplained credits. A £50,000 inbound with the reference “TRANSFER” and no remitter detail is a flag, not a comfort. Ask the bank for remitter details if the PDF strips them. Or attach the originating account statement that shows the matching outbound.
HMRC’s customer due diligence overview treats source of funds as part of understanding the purpose and nature of the relationship and as part of ongoing monitoring where risk requires it. Statement PDFs with the customer’s name, sort code, account number and running balance are the baseline. Screenshots that crop the name off fail. Joint accounts need the other name explained. Company accounts need to match the borrowing SPV or the director who is injecting equity.
Retained interest and fees paid from cash need the same trail as the deposit. If the client is wiring £40,000 for interest reserve and entry fee, that pot is funds for the relationship too. Do not treat it as “just fees” and leave it off the schedule.
Auction deposits already paid sit in the same zip. Name the auctioneer, the lot, the amount and the account that paid it. Our auction legal pack note covers the title papers. The deposit trail still has to clear before auction finance can complete inside twenty-eight days.
Sale receipts director loans and gifted equity papers
Most clean deposits come from one of four places. Prior sale. Director loan into the SPV. Gifted equity from a connected person. Refinance or redemption surplus on another charged asset.
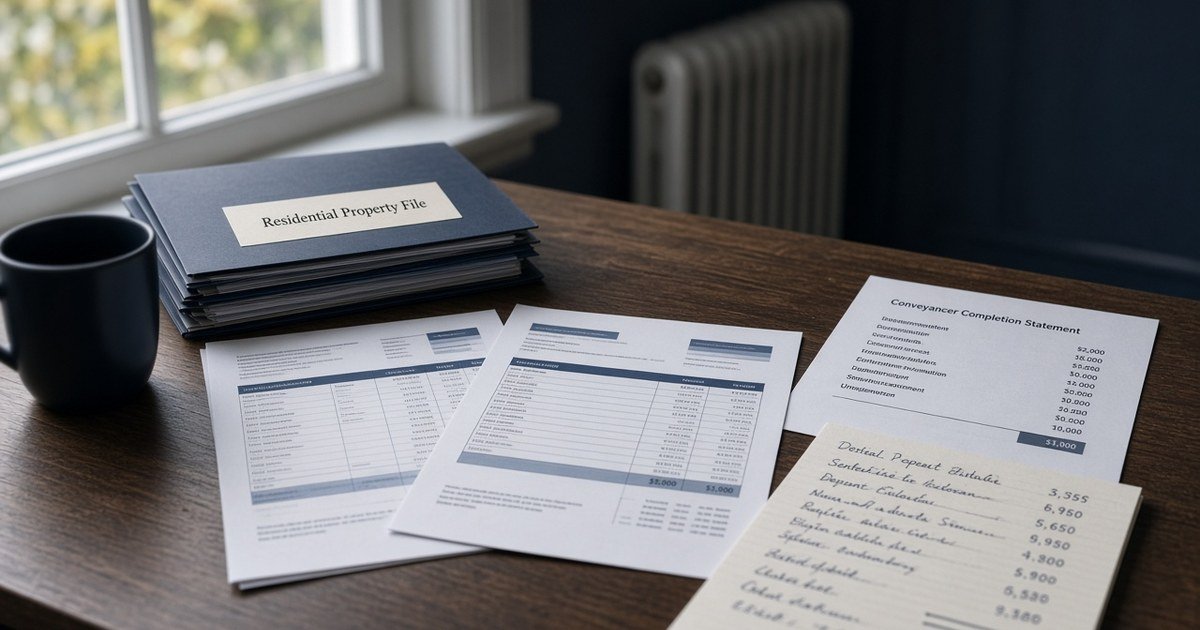
For a prior sale, attach the completion statement from the conveyancer, the Land Registry transfer evidence if you have it and the bank credit that matches the net proceeds. Dates have to line up. A completion in March and a deposit credit in September needs the intervening statements that show the money sat in the same account. Credit will ask where it went if a gap appears.
For a director loan, attach the board minute or loan agreement, the director’s own statements showing the outbound and the SPV account showing the inbound. Names must match. A transfer from an unnamed personal account into the SPV with no minute is not a director loan. It is an unexplained credit.
For gifted equity, name the donor, the relationship, the amount and whether it is a gift or a soft loan. Attach the donor’s identity, the gift letter and the donor’s statements that show the outbound. Third-party money without a gift letter stalls almost every file. HMRC’s estate agent sector guidance flags gifted deposits and last-minute funding changes as points that need documented rationale. Specialist desks take the same view even though the product is unregulated commercial bridging rather than estate agency work.
For refinance surplus or a redemption on another asset, attach the redemption statement, the completion or remortgage statement and the credit into the account funding this deal. Do not point at equity on a different title and expect credit to invent the cash trail.
Cash withdrawn and redeposited is the slowest path. Large cash withdrawals followed by a matching deposit invite questions the file rarely answers well. Prefer bank-to-bank evidence. If cash genuinely sat in a safe, say so early and expect enhanced checks.
Overseas remittances and third-party payments credit flags
Overseas money is not an automatic decline on a commercial file. Silence about overseas money is.
Say on page one if any deposit, equity or fee cash is coming from outside the UK. Name the country, the remitting bank, the account holder and the FX route. Attach the foreign statements with a translation where the language is not English, plus the UK receipt that matches. Expect more time. Budget it into an auction clock before the hammer, not after.
Third-party payments need the same honesty. Money arriving from a connected company, a family member or a business partner is still third-party until the trail and the relationship are on paper. Payments from accounts that do not match the borrower or named donor usually bounce back from the lender’s solicitor. Fix them in the first zip.
Structuring that splits one deposit into many small transfers to stay under a perceived threshold looks worse than one clear credit. HMRC’s responsibilities guide warns about linked transactions broken up to avoid checks. Credit reads patterns. One honest transfer beats five awkward ones.
Politically exposed persons and high-risk country links push the file into enhanced checks. Wealth papers then sit beside funds papers. Do not bury a PEP connection in a footnote. Put it on the one-pager so senior sign-off can start while the rest of the pack is still assembling.
Portfolio finance files often have several pots. Rent from one SPV. Sale proceeds from another. A director loan into a third. Put each pot on its own row. Cross-collateral is not a licence to pool unexplained credits across companies. Our rent roll pack covers income evidence. It does not replace the deposit trail for the equity the borrower is injecting.
How the SOF pack sits beside SPV title and exit evidence
Source of funds is one zip in a larger file. It does not replace title, exit or security papers.
Title still has to be chargeable. Send the register and plan. Leasehold needs term, ground rent and consent-to-charge. Existing charges need balances. Exit still needs proof. A sale memo without a diary fails for the reasons in our sale-exit pack. A refinance exit still needs a live illustration. Development finance take-outs still need cost and drawdown papers. Multi-let stock still needs licensing where our HMO pack applies.
What SOF uniquely answers is simple. Whose money is clearing the gap between the advance and the total cash needed on day one. Credit can like the asset and still refuse to fund until that gap has a trail.
Name the receiving account early. Completion funds and deposit top-ups should leave an account in the borrower’s or SPV’s name wherever the risk profile requires it. Last-minute switches of paying account are a classic flag in property AML guidance. If the paying account must change, say why and refresh the statements before drawdown week.
StatusKWO works with broker partners who want a same-day DIP on files that already answer the money questions. Incomplete deposit schedules come back as question lists. That is slower than spending twenty minutes on the trail.
What brokers should send with the first deposit trail
Use this as the zip order for source-of-funds evidence.
- One-page deal summary with address, loan, term, use of funds, exit and a table of every cash pot the borrower is injecting.
- Three months of statements for each account holding or sending those pots, with the customer’s name visible.
- For sale proceeds, the conveyancer completion statement and the matching bank credit.
- For director loans, the board minute or loan agreement plus outbound and inbound statements.
- For gifts, the gift letter, donor identity and donor statements showing the outbound.
- For refinance or redemption surplus, the redemption or remortgage statement and the matching credit.
- For overseas money, foreign statements, remitter details, FX evidence and the UK receipt.
- A short source-of-wealth paragraph when the deposit is large against known income or when enhanced checks already apply.
- Identity and company papers from the general bridging and SPV packs, sitting beside the trail rather than instead of it.
Rates and fees still run from the published schedule once the trail is credible. A clean LTV with a dirty deposit still costs entry fee, exit fee and monthly interest from 1.25%. Stretching the term does not cure an unexplained credit. It usually makes the file look worse because more interest cash then needs its own origin story.
If the money is already in the right account with a clear trail, say so and attach the PDFs. If a piece is still in transit, name it and give a date. Hope is not a remittance advice.
Frequently asked questions
Is a UK bank statement enough to clear source of funds on a bridge?
No. Statements prove possession and transit. HMRC’s source-of-funds manual is clear that knowing the money sat in a UK account is not enough. Credit still wants the origin of that credit, whether sale proceeds, director loan, gift, salary savings or another evidenced route.
What is the difference between source of funds and source of wealth?
Source of funds is the money for this transaction. Source of wealth is how the customer built their wider assets. Most bridging deposits need a funds trail. Wealth papers arrive when the deposit looks large against known income, when the structure is complex, or when enhanced due diligence already applies.
Can overseas deposit money fund an unregulated commercial bridge?
Often yes, if the trail is complete. Name the country and remitter on page one. Attach foreign statements, FX evidence and the matching UK credit. Expect more time than a simple UK sale receipt, especially on a twenty-eight-day auction completion.
Do retained interest and fees need a source-of-funds trail?
Yes when the borrower is paying them from cash rather than from retained loan proceeds. Those sums are still funds used in the relationship. Put them on the deposit schedule and attach the same account evidence.
When should brokers send the SOF zip relative to the DIP?
Send the schedule and the main statements with the first enquiry whenever they exist. A DIP can issue on a thinner pack, but completion will not. The brokers who clear inside a few days keep collecting the trail while the valuer is on site rather than waiting for the solicitor to ask.