The covering email still says ninety days to clear. The board has been live for fourteen weeks. Two offers died after survey and the asking price has already been cut twice. Credit does not decline the bridging loan on LTV alone. It stalls on a sale memo that never showed the diary, the cuts or the Plan B.
StatusKWO prices short commercial facilities for professional investors, developers and corporate borrowers. Main-home owner-occupier files sit outside that set. The published schedule currently shows a monthly rate from 1.25%, an entry fee of 2%, an exit fee of 1.5%, LTV up to 85%, loans from £10,000 to £10,000,000+ and terms up to 16 months. Those figures sit on the product sheet. They are not a promise that a soft private-treaty exit prices at the floor.
The sale memo gap that stalls a DIP
A tidy decision in principle request is not a funded repayment. Credit needs the same papers the estate agent and conveyancer already hold. A one-line “sale in progress” box does not underwrite a clock.
Our general bridging pack note covers identity, companies and source of funds. Tuesday’s BDLA Q2 note put a sector number under stretched sale exits. The earlier slow sales and firmer refinance piece flagged the same pressure from the broker side. This page is narrower. It is the sale-exit evidence zip a specialist desk wants before it prices a private-treaty repayment.
Start the enquiry with one page. Address and title number. Gross and net loan. Term. Asking price and last cut. Days on market. Named agent. Named conveyancer. Current status (live, under offer, sold subject to contract). Named Plan B if the sale slips. Then attach the marketing papers before the glossy brochure. Credit can read a brochure in five minutes. They cannot invent a viewing log from a covering email.
GOV.UK’s public selling a home overview is blunt about the average clock. Selling takes about five months on average and longer inside a chain. That is not a consumer scare line for this desk. It is why a ninety-day memo without evidence looks thin when the asset has already been live for a quarter.
Marketing diary price cuts and days on market credit must see
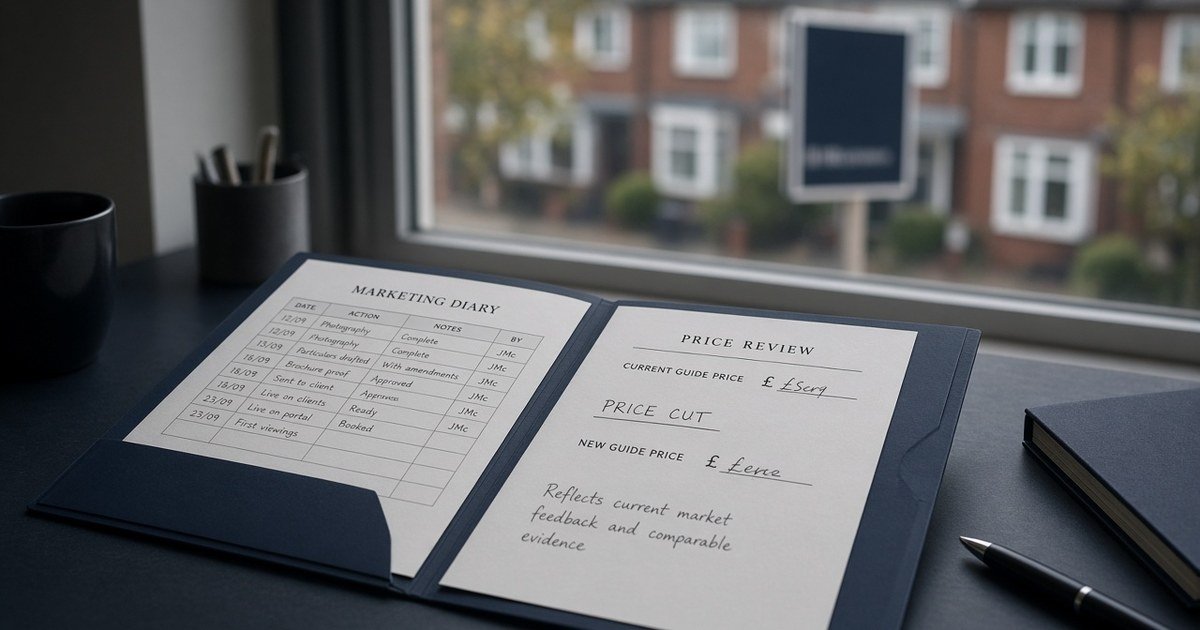
Private-treaty Plan A starts with a dated diary. When did the board go up. What was the first asking price. Which cuts landed and on which dates. How many days has the asset been live at each price. Who is the listing agent and on what sole or multi-agency basis.
Put the diary on page one. Do not bury it behind the valuation PDF. Credit reads days on market before it reads the residual. An asset that has sat past ninety days is not automatically declined. A pack that pretends it has not sat at all usually is.
Ask the agent for the comparative evidence behind the current ask. GOV.UK’s how to sell a home guide tells sellers to ask the agent for evidence to support a valuation, including similar properties recently sold. The same ask belongs in a specialist pack. A high board number is not a clearance date.
Price cuts already taken should be listed, not paraphrased. Credit wants the trail. A broker summary that says “priced to sell” after two silent cuts wastes a day. Write the old ask, the new ask and the date of each change. If the next cut is already agreed with the seller, put that in too. Hope is not residual equity.
Auction exits are a different clock. Fixed completion dates and legal packs sit in our auction legal pack note. Do not dress a soft private-treaty file as an auction finance timeline. The papers below assume an open-market sale, not a hammer date.
Viewing feedback offers and residual after the last cut
The diary alone is not enough. Credit wants the feedback that killed the last two offers and the residual after the last cut.
Ask the agent for the viewing log. Dates. Number of viewings. Written feedback where it exists. Reasons the last offers fell away after survey, mortgage or chain. Credit reads that faster than another broker paragraph. If buyers walked because the EPC, lease term or works bill did not match the particulars, say so. Silence forces the underwriter to guess.
Offers should be tabulated. Date, price, conditions, status. An offer that was never mortgageable at the stated price is not an exit. An offer that died after a low survey is a valuation problem, not a marketing flourish. Put the survey figure in the pack if the buyer shared it. Credit will ask anyway.
Re-cut the residual yourself before the valuer does it. Take the current ask or the best live offer, deduct selling costs, redeem any first charge and show what clears the proposed bridge. If the residual only works at last spring’s ask, the file is already underwater on paper. Stretching the term does not invent a buyer. It stacks interest.
For portfolio finance, one stalled sale can block a take-out meant to clear several lines. Put the slow asset on its own row. Do not hide it behind stronger stock. Cross-collateral is not a licence to ignore days on market on the weak line.
Conveyancer EPC and title papers that move a private treaty clock
Marketing papers move the buyer. Legal papers move completion. Credit wants both in the first zip when repayment sits on a sale.
Name the conveyancer on page one. Attach the retainer if it exists. A seller who has not instructed anyone yet has not started the legal clock, whatever the board says. GOV.UK’s sell guide is clear that you should choose a legal representative shortly before the property goes on the market or as soon as it is listed, because that reduces delays. The same logic sits on a specialist file.
Title still has to be chargeable and saleable. Send a current register and title plan. GOV.UK’s Land Registry search explains how to obtain them. Credit still wants the PDFs in the pack, not a promise that someone will download them later. Leasehold needs the remaining term, ground rent, service charge position and any consent-to-charge or alienation clause that can stall a buyer’s solicitor.
An Energy Performance Certificate belongs in the pack when the asset is marketed as a dwelling. Missing or expired EPC paperwork is a common reason viewings stall. Put the certificate in the zip before credit has to ask. Sitting tenants, licence gaps and soft compliance evidence create the same delay on investment stock. Our HMO licensing pack and rent roll pack cover those files. Do not leave tenancy papers out of a sale-exit zip when the buyer is purchasing with tenants in situ.
Works required before a mainstream buyer can complete are an exit problem. If the particulars promise a light refresh and the survey will show a new roof, say so on page one. Credit would rather price a short works tranche than discover the sale cannot complete without one.
Subject to contract status that is not yet an exit
Sold subject to contract is progress. It is not repayment.
GOV.UK’s sell guide is explicit. The property is not legally sold until written contracts are exchanged. Until then, either side can walk. Credit treats STC as a live risk, not a cleared exit. The pack should say so without spin.
When the file is under offer or STC, send the memorandum of sale or agent confirmation, the agreed price, the proposed exchange and completion windows, the buyer’s solicitor details and whether the buyer is cash or mortgage-dependent. If the buyer needs a mortgage that no longer clears the agreed price after a survey, the exit has already slipped. Put the shortfall on the page. Do not wait for completion week.
Chains lengthen clocks. GOV.UK notes that selling takes longer inside a chain. Name the chain length if the agent has it. A four-leg chain with a first-time buyer at the bottom is a different risk from a cash buyer with no onward purchase. Credit does not need a novel. They need the legs counted.
Exchange is the moment the sale becomes binding. Until then, Plan A remains contingent. A DIP issued against an STC memo still needs a Plan B that can clear the bridge if the buyer withdraws. Brokers who treat STC as cash usually come back a fortnight later asking for an extension.
Plan B refinance fallback that still has to clear the bridge
Sale exits fail. The pack that admits that early prices faster than the pack that discovers it on month four.
Plan B usually means a term refinance, a switch to auction or a sale of a different charged asset. Each path needs its own papers. A one-line “refinance available” box is not a fallback.
For a refinance Plan B, attach a live term illustration dated after the latest rate moves, not the sheet from the day the bridge was first discussed. Stress the LTV and rental cover the term lender actually uses now. Show the equity needed if the advance falls short of the bridge redemption. Our packaging note already lists the company and identity papers. Add the revised illustration to that zip.
Auction as Plan B is only real if the legal pack can clear a fixed completion and the borrower can fund the deposit and tax. Point at the auction finance product page and the legal pack checklist. Do not invent a hammer date without the catalogue deadline and special conditions.
Development finance take-outs are a different product. If the bridge is only buying time until a build facility draws, say so and send the works schedule and planning position. Do not squeeze a ground-up programme into a sixteen-month sale memo.
StatusKWO works with broker partners who want a same-day DIP on files that already answer the exit questions. Incomplete sale memos come back as question lists. That is slower than spending twenty minutes on the diary.
What brokers should send with the first enquiry
Use this as the zip order for a private-treaty sale exit.
- One-page deal summary with address, title number, loan, term, ask, days on market, agent, conveyancer, status and named Plan B.
- Marketing diary with go-live date, asking prices, cut dates and current days on market.
- Viewing log and written feedback on failed offers.
- Offer table with dates, prices, conditions and status.
- Residual calculation after selling costs and any senior charge.
- Current Land Registry register and title plan.
- EPC and, where relevant, tenancy or licensing papers.
- Conveyancer details and retainer if instructed.
- Under-offer or STC papers if the asset has moved that far.
- Live Plan B refinance illustration or auction fallback note.
Identity, company papers and source of funds still sit in the general bridging pack. They are not replaced by a sale diary. They sit beside it.
Rates and fees only move when the exit is credible. A soft ask with no diary still costs entry fee, exit fee and monthly interest from 1.25% on the published schedule. Stretching the term because the board is quiet does not make the residual stronger. It usually makes it weaker.
If the sale clears inside the term, redeem on time and close the file. If it does not, bring the revised diary and the Plan B papers before the last month, not after interest has already stacked.
Frequently asked questions
Is a sold subject to contract memo enough to underwrite a sale exit?
No. STC means the parties have agreed a price on paper. It does not mean contracts are exchanged. Either side can still walk. Credit wants the memorandum, the buyer type, the proposed exchange window and a Plan B that can clear the bridge if the buyer withdraws.
How many days on market will a specialist desk accept?
There is no single cut-off. An asset live past ninety days can still clear if the diary, cuts and residual are honest. A pack that hides the days on market usually stalls first. Put the number on page one and re-cut the residual after the last ask.
What Plan B papers should sit behind a private-treaty sale?
A live term refinance illustration dated after recent rate moves, or a real auction fallback with deposit and legal-pack capacity. A sentence that says refinance is available is not enough. Show the advance, the stress rate and the equity needed if the take-out falls short of the bridge.
Do I need a conveyancer instructed before the DIP?
Credit can issue a DIP while the seller is still choosing a firm. Funding and repayment both move faster when the conveyancer is already named. GOV.UK advises instructing early to reduce delay. Put the name in the first email when you have it.
Does StatusKWO lend on consumer sale-exit bridges?
No. StatusKWO’s facilities are unregulated commercial lending for professional and corporate property borrowers. Owner-occupier main-home cases sit outside that perimeter. Use the DIP engine only for commercial investment and development stock that fits the product set.