The residual still books clean ground. Build cost is elemental. GDV looks fundable. Then credit asks for the Phase 1 desk study and the broker forwards a free environmental screenshot with no walkover, no conceptual site model and no competent-person name. The development finance enquiry does not fall over on LTV. It stalls on ground risk the desk cannot price.
The brownfield residual that still treats contamination as a solicitor footnote
A tidy decision in principle on GDV alone is not a funded first draw. Credit needs to know whether the title carries former industrial use, made ground, tanks, nearby landfills, ground gas or other contaminant linkages that change cost, programme and exit. Our bridging pack note covers identity, companies and exits. The planning decision notice pack covers consent and conditions. The flood and environmental search pack covers water risk and CON29 lines. Contaminated land sits in its own folder. It is the Phase 1 and remediation trail a specialist desk wants before it prices an unregulated commercial works facility on land that may be affected by contamination.
Start with one page. Site address and title number. Current and proposed use. Known former uses. Local planning authority. Planning reference and decision date. Phase 1 status and report date. Competent person or firm named on the report. Conceptual site model summary. Whether Phase 2 is recommended. Remediation strategy status if any. Gross and net facility. Named exit. Borrower name. Then attach the PDFs. A covering line that says “brownfield known, searches fine” does not underwrite a programme.
Late papers burn interest. A residual rewritten after offer because nobody modelled remediation is how facilities lose a month. That rewrite is avoidable. Brokers who treat ground risk as a solicitor chore after valuation often discover the bill when the contractor is already priced. Send the Phase 1 with the first appraisal. Pricing then stays about cost and exit.
StatusKWO prices commercial works facilities for professional developers, investors and corporate SPVs. Main-home owner-occupier lending sits outside that book. Short commercial facilities on the published schedule currently show a monthly rate from 1.25%, an entry fee of 2%, an exit fee of 1.5%, LTV up to 85%, loans from £10,000 to £10,000,000+ and terms up to 16 months. Development facilities are priced on the scheme. Treat those bridging figures as a schedule reference only.
What a Phase 1 preliminary risk assessment must actually contain
A commercial environmental search is useful factual fuel. It is not a Phase 1 on its own.
GOV.UK’s land affected by contamination guidance is plain. If there is reason to believe contamination could be an issue, applicants should provide proportionate site investigation information prepared by a competent person. That risk assessment should determine whether contamination exists, its nature and extent, the risks it may pose and to which receptors. The National Quality Mark Scheme accredits competent persons for land contamination reporting. Credit wants the named competent person on page one. A broker paraphrase of “looks clean” fails.
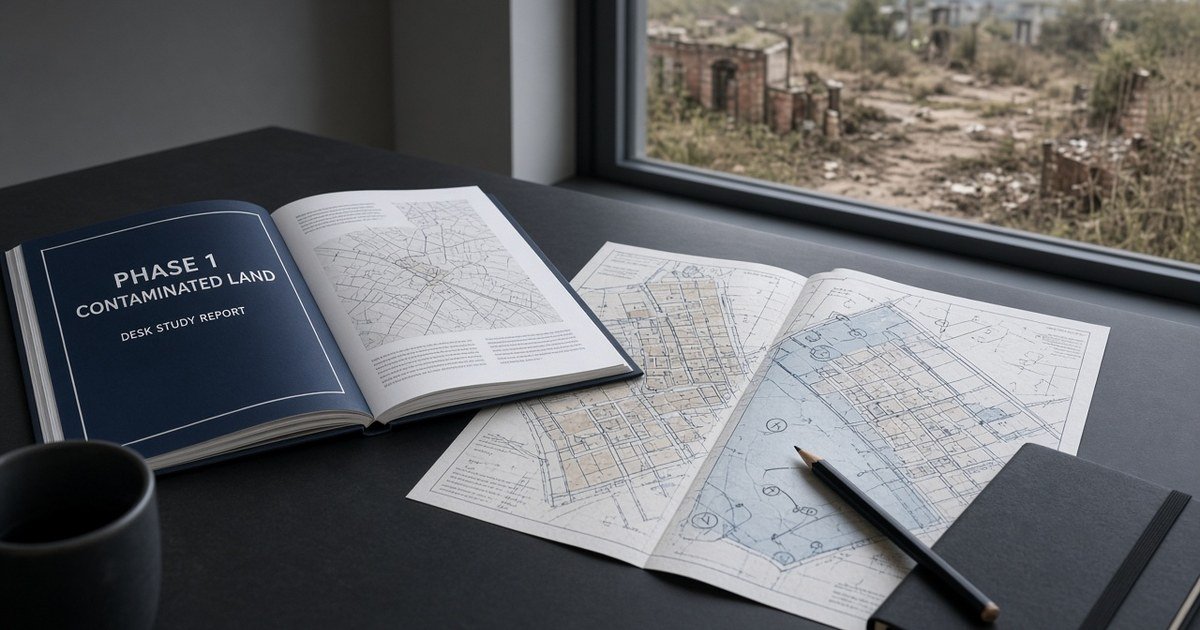
At the first stage an authority may require at least a desk study and site walk-over. That pack should build a conceptual model of sources, pathways and receptors. It should also show how pollutant linkages can be broken. Unless that initial assessment clearly shows risk can be reduced to an acceptable level, further investigation follows. Environment Agency Land Contamination Risk Management guidance frames the same first step as a preliminary risk assessment inside Stage 1. Brokers who paste a Landmark or Groundsure PDF and call it Phase 1 usually get a chase. Local authority notes often say the same thing in blunt terms. Credit will too.
A usable Phase 1 for a specialist desk usually shows all of the following.
- Site location plan and red-line boundary that match the title.
- Desk study of current and historic uses on and around the site, including maps, directories, landfill data, permits and pollution incidents where available.
- Geology, hydrogeology and hydrology setting, including aquifers and controlled waters where relevant.
- Site walkover notes and photographs, not a desk-only guess.
- Conceptual site model naming sources, pathways and receptors.
- Preliminary risk ranking of contaminant linkages.
- Clear recommendation on whether intrusive Phase 2 work is required.
- Named author, firm and competence route.
Match the address on the report to the title and the valuation instruction. Wrong plot numbers create legal delay that a twelve-month facility does not absorb. If the Phase 1 covers a wider estate than the charged title, draw the red line. Credit needs to know which ground story travels with which security.
Former industrial areas are the usual suspects. Countryside titles are not automatically clean. GOV.UK notes contamination can sit in rural locations through moved material, inappropriate spreading or natural background hazards such as radon and elevated metals. Say what the desk study found. Do not invent a clean story because the site now looks like scrub.
Made ground deserves its own sentence on page one. Fill, ash, demolition arisings and imported hardcore change both foundation design and contamination risk. A Phase 1 that shrugs past made ground while the trial pits later show black ash will rewrite the residual twice. Put the historic map extract next to the walkover photos when the surface already looks disturbed.
When credit asks for Phase 2 intrusive papers and remediation cash
Phase 1 is the gate. Phase 2 is where cash becomes specific.
If the preliminary assessment leaves credible contaminant linkages open, credit will ask for intrusive investigation before treating remediation as a soft contingency. That usually means soil, groundwater and ground-gas sampling against a written scope, laboratory results and a quantitative risk assessment against published screening criteria. The report should say what was found, where it sits and what it means for the proposed use. A borehole log without interpretation is not a risk assessment.
Remediation strategy belongs next to the cost plan. Credit wants the break in the pollutant linkage named. Cover systems. Dig and dispose. In-situ treatment. Gas protection. Validation sampling. Each line needs a cost and a programme slot. Our build-cost and drawdown pack already wants elemental spend. Remediation sits at the front of that sequence when ground works cannot start cleanly without it. A first draw that funds slabs while validation is still outstanding is already soft on paper.
Treatment and redeposit of contaminated soils can need an environmental permit when the soils are waste. GOV.UK’s contamination planning guidance flags Environmental Permitting beside planning and Building Regulations. Put the permit route on page one when the strategy relies on treating or moving soils on site. Silence forces the underwriter to assume delay.
Part 2A of the Environmental Protection Act 1990 is a separate regime for identifying and remediating land that meets the statutory definition of contaminated land. Planning still has its own job. After remediation, land should not be capable of determination under Part 2A as a minimum. Credit does not need a lecture on the statute. Credit needs three facts on page one. Whether the title already sits on a Part 2A list. Whether the Environment Agency has an interest because of controlled waters. Whether the proposed remediation meets the planning and Building Regulations tests for the new use.
Outline permissions do not wipe the ask. GOV.UK is clear that before granting outline consent an authority still needs to understand the contaminated condition of the site and be confident remediation is viable. A facility priced against outline consent with “Phase 1 later” in the residual is hope. Attach what exists. Say what remains.
Estimated remediation ranges are fine when the basis is visible. A figure pulled from a neighbour’s scheme with no scope note is not. Show the consultant’s estimate, the contingency and the Phase 2 date that will harden the number. Credit can live with a range. Credit cannot live with a blank cell.
Asbestos in soils and buildings sits in the same honesty test. A demolition method statement that ignores asbestos survey status will stall both Building Control and the monitor. Put the survey reference next to the remediation strategy when strip-out is in the first phase. Do not leave that ask for the week the skip arrives.
Planning conditions Building Control and how contamination clocks sit beside them
Contamination papers sit beside consent papers. They do not replace them.
Planning conditions often stage the work. Site characterisation. Submission of a remediation scheme. Implementation of the approved scheme. Monitoring and maintenance. Map each condition against the facility calendar. A pre-commencement contamination condition that still hangs will block lawful start even when the contractor is booked. Attach discharge evidence when a stage is cleared. Our CIL and section 106 pack covers contribution cash. Contamination conditions are a different clock. Put both on page one when both exist.
Building Regulations still require reasonable precautions against contaminants in ground to be covered by buildings and associated ground. A planning discharge letter does not automatically prove Building Control comfort. Higher-risk residential schemes may also need the Gateway 2 pack. Ground gas protection design belongs in that story when the Phase 2 report calls for it. Listing, party walls and ordinary planning consent sit in their own packs. Do not ask the underwriter to infer one regime from another.
Flood and drainage design can collide with remediation. Sustainable drainage that disturbs contaminated made ground without a method statement is a classic late surprise. Keep the flood search pack and the Phase 1 in the same zip when both risks sit on the title. Credit would rather price both early than rediscover one mid-monitor.
Light works that truly belong on a short bridging loan still need honesty when former use is obvious. A purchase bridge against a former petrol filling station with no Phase 1 is not a cleaner file just because the borrower calls the works “cosmetic”. Product choice follows the bridge versus development split. Mis-labelling a remediation-heavy conversion as a sixteen-month light refurb wastes the first week.
How missing ground papers hit drawdowns sale exits and refinance
Interest accrues while consultants wait for access. A Phase 2 that needs live services isolated, tenants moved or trial pits in a live yard can take longer than the broker hoped. Put the access plan next to the investigation scope. Hope is not a float.
Drawdowns stall when validation is thin. Monitors will not sign a clean certificate over open excavations that still wait for confirmatory sampling. Keep remediation validation letters with the draw request. A borrower who spends the remediation budget and then cannot prove the break in the linkage usually faces a pause, not a shrug.
Sale exits need buyer solicitors and warranty providers who will accept the ground trail. Missing Phase 1, undischarged contamination conditions and unexplained made ground all slow a disposal. New or converted dwellings often need a structural warranty route that asks about contamination and gas protection. Put the intended warranty provider on page one if the policy is not yet bound. Our build-cost pack already flags NHBC and equivalent cover. Ground papers sit beside that ask.
Refinance exits face term-lender credit committees that repeat the same questions. A bridge that funded strip-out without a Phase 1 can leave the borrower with a prettier shell and a blocked take-out. Keep the Phase 1, Phase 2, remediation strategy and validation with the valuation and the EPC. Do not assume a term lender will “take a view” on a former works yard with no conceptual model.
Auction finance clocks make the same point earlier. Catalogue legal packs vary. Some lots include a recent desk study. Some include almost nothing beyond title and special conditions. Our auction legal pack note already asks for searches and special conditions. If the catalogue whispers former industrial use, put the Phase 1 in the first zip before the bid. A twenty-eight day completion does not wait for a walkover that should have been booked before the room.
Portfolio finance take-outs that rely on early units need the contaminated plot marked on the schedule. One title with open Phase 2 recommendations should not vanish inside a ten-asset workbook that says “searches fine”. List each title. List each report date. List which remediation cash sits against which plot.
Phased schemes hide the weak plot. A multi-phase consent can clear Phase 1 on the plot that sells first while plot two still waits for gas monitoring. Mark which phase carries which investigation. Averaging ground risk across the estate hides the title that kills the refinance.
Broker packaging speed is still a credit advantage. Files that arrive with the Phase 1, conceptual model, Phase 2 status and remediation cash map get priced. Files that arrive with “environmental TBC” in the subject line wait. If you need a quick steer before a full application, use the decision in principle engine with the Phase 1 attached. Do not send the GDV alone and promise ground papers later.
What brokers should put in the first contamination zip
Send one zip. Name it with the site address and “contamination pack”. Keep the one-pager on top.
- One-pager with address, title number, former and proposed use, Phase 1 status, Phase 2 status, remediation cash, facility size, exit and borrower.
- Full Phase 1 preliminary risk assessment PDF with desk study, walkover, conceptual site model and recommendations.
- Commercial environmental search extracts only as supporting facts, not as a substitute for the Phase 1.
- Phase 2 intrusive report and quantitative risk assessment when already complete or clearly required.
- Remediation strategy, costed programme and any environmental permit route for soil treatment or redeposit.
- Planning decision notice and contamination conditions with discharge letters where stages are cleared.
- Building Control or gas-protection design notes when the report calls for them.
- Title plan red line that matches the investigation boundary.
- Flood and drainage papers when water risk sits beside ground risk on the same title.
- Named exit papers showing how warranty, sale or refinance will read the same ground trail.
If the lot is an auction purchase, add the memorandum, deposit trail and special conditions beside this pack. If contributions also bite, add the CIL and section 106 notices. If the scheme is higher-risk residential under the Building Safety Act regime, add the Gateway 2 papers and say so on page one.
Brokers who want a named contact for packaging can start on the brokers page. The desk still prices from documents. A warm introduction does not replace a missing desk study.
Frequently asked questions
Is a commercial environmental search enough to price development finance on a former industrial site?
No. A search can feed the desk study. Credit still wants a Phase 1 preliminary risk assessment with a walkover, a conceptual site model and a competent-person recommendation. Local authorities and specialist desks both treat a search-only pack as incomplete when contamination could be an issue.
When does a Phase 1 force a Phase 2 before first draw?
When the preliminary assessment leaves credible contaminant linkages open for the proposed use. Credit will not treat an open recommendation for intrusive work as a soft contingency if ground works or residential receptors sit in the programme. Attach the Phase 2 scope and timing if the report is not yet final.
Does outline planning permission remove the need for contamination evidence?
No. Outline consent still needs the authority to understand the contaminated condition of the site and be confident remediation is viable. A facility pack should show what investigation already exists and what remains before detailed consent and first draw.
Can a short bridging loan ignore Phase 1 if the borrower only wants light works?
Not when former use or site evidence points to contamination risk. Light works on a clean title are one file. Light works on a former fuel site with no Phase 1 are another. Product choice does not erase ground risk. Put the papers in early or expect a pause.
What if remediation costs are still estimated when we apply?
Say so on page one and show the basis of the estimate. Credit can price a transparent range with a clear Phase 2 path. Credit cannot price a blank cell labelled “TBC” against a residual that already spends every pound of equity.